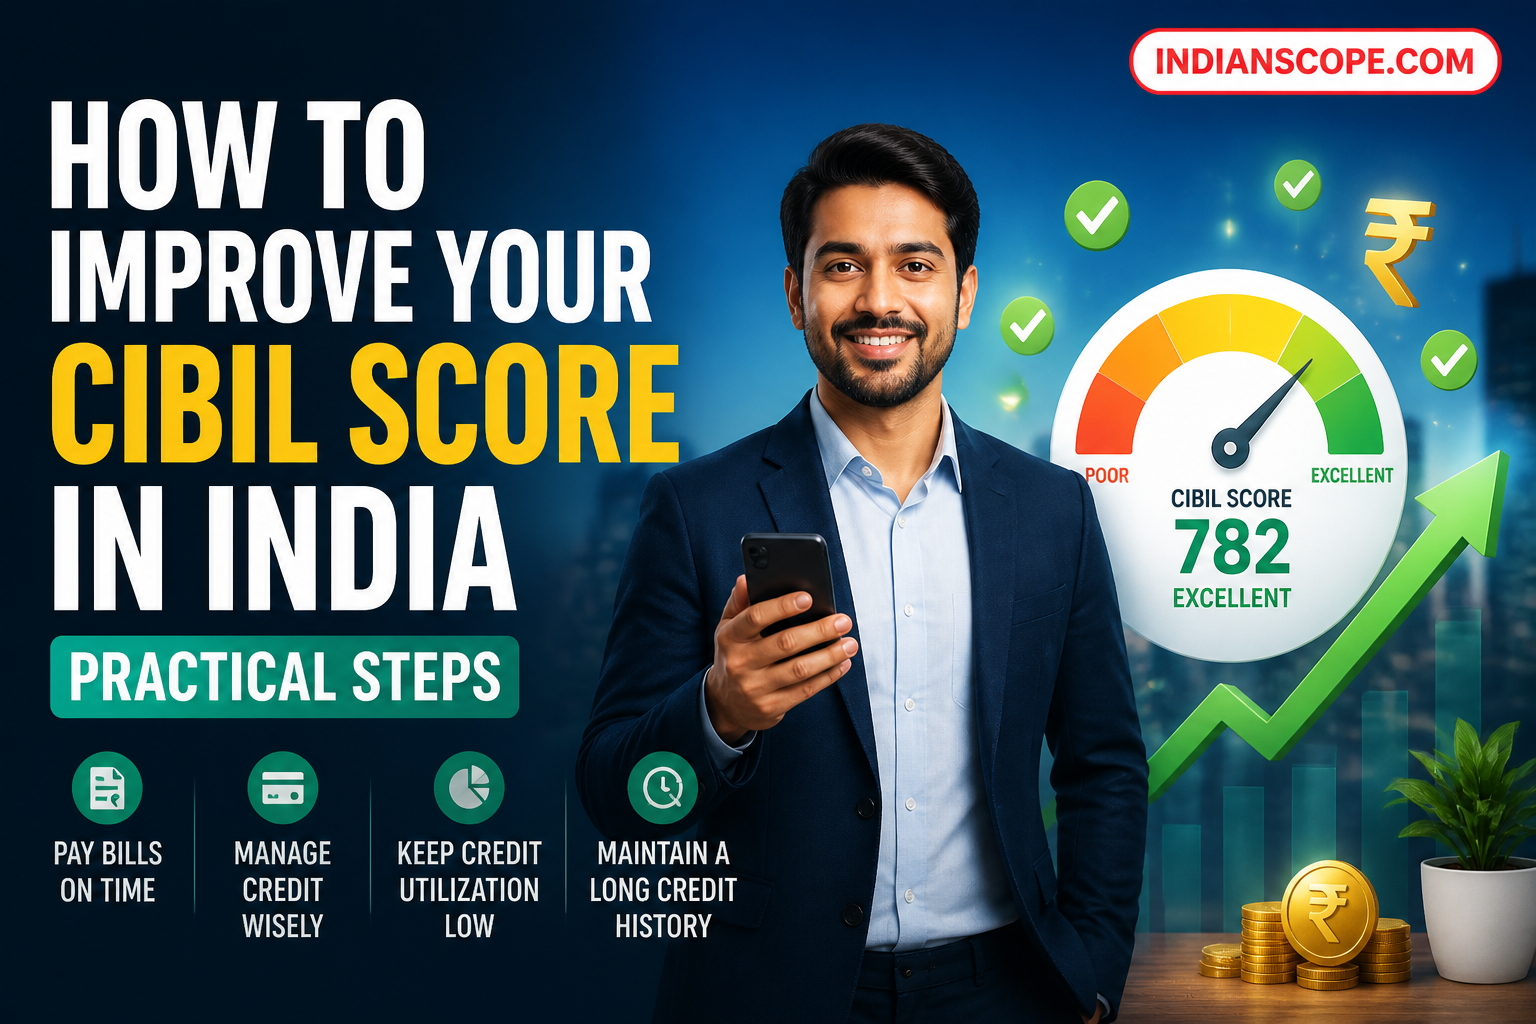
A stronger credit profile can make it easier to apply for loans or credit cards, although lenders consider more than a score when making decisions. If you are wondering how to improve your CIBIL score in India, start with the basics: review your credit report, pay every bill and instalment on time, and avoid using most of your available card limit. These habits cannot guarantee a particular score or a quick result, but they can help build a reliable credit record over time. Accurate reporting by lenders matters too. Here is a practical guide to what to review and what to do next.
What is a CIBIL Score, and why does it matter?
A CIBIL Score is a three-digit number generated from information in your CIBIL credit report. TransUnion CIBIL says the score generally ranges from 300 to 900. Lenders may use it as one factor when assessing a credit application, alongside their own eligibility rules and other information. A particular score does not guarantee approval.
Your score reflects patterns in your credit history, not just your income or savings. Relevant factors include repayment history, credit utilisation, the length and mix of credit, and credit enquiries. Paying on time and managing existing borrowing are useful starting points; opening new accounts simply to try to change your score is not a reliable strategy.
1. Review your credit report before changing anything
Check your CIBIL report for accounts you do not recognise, incorrect personal details, wrong balances, duplicate accounts, or payment records that do not match your own records. A score can only reflect the information reported to the bureau, so correcting an error is an important first step. Reviewing the report can also help you spot an old account that is still showing as unpaid or one you believed was closed.
Compare the report with your loan and card statements, as well as your payment confirmations. Check the account status, outstanding balance, payment history, and whether accounts you have closed are shown accurately. If something looks unfamiliar, contact the lender or bureau to understand it rather than assuming it is a harmless display issue.
2. Pay every instalment and card bill by its due date
Repayment history is a key part of the information relevant to a CIBIL Score. Pay loan instalments and credit-card bills by their due dates, using a simple system to stay organised if needed. Preventing late payments is generally more practical than trying to repair their impact later.
Set calendar alerts several days before each due date. You can also use standing instructions or automatic payments where available, but check that the linked account has enough funds and that each payment has gone through. Paying at least the minimum due on a credit card may help avoid a missed-payment record, but it does not clear the full balance or prevent interest from accumulating. Pay the full amount due when you can, and review your statement even if you use automatic payments.
3. Keep credit-card balances modest compared with limits
Credit utilisation is the share of available revolving credit that you are using. For example, if your card limit is ₹1,00,000 and the reported balance is ₹70,000, your utilisation is 70%. TransUnion CIBIL identifies utilisation as a relevant factor and advises keeping it low.
No specific utilisation percentage guarantees a score increase. A sensible approach is to avoid routinely using most of your available limit. Pay down balances where your budget allows, and consider spreading necessary spending across the billing cycle rather than letting a high balance accumulate. Do not spend more or take on debt simply to demonstrate activity. A higher credit limit is not a reason to increase your spending, and repeated requests for limit increases may not be appropriate for everyone.
4. Apply for credit selectively
A credit enquiry is a record associated with a lender checking your credit information, commonly after a credit application. Several applications in a short period may result in multiple enquiries. CIBIL advises borrowers to avoid making multiple credit applications within a short time.
Before applying, check whether the product suits your needs and whether you are likely to meet the lender’s stated eligibility requirements. Compare options first, then apply deliberately rather than submitting applications to many providers at once. Checking your own report is different from a lender’s enquiry for a credit application; use the bureau’s official consumer service and follow its current instructions.
5. Build a steady history; do not borrow just for a credit mix
The length and mix of credit are among the factors CIBIL identifies as relevant. A responsible track record across credit types may form part of a broader credit history, but this does not mean you should take out a loan you do not need. Unnecessary borrowing can add repayment commitments and costs without guaranteeing a score benefit.
If you already have credit, focus on managing it responsibly and keeping accounts accurate. If you have limited credit history, be cautious about offers that promise a fast score increase. Choose credit only when it serves a genuine need and the repayments fit your budget. A healthy financial decision is more important than trying to manufacture a particular mix of accounts.
6. Dispute inaccurate information and follow up
If your report contains an error, raise a dispute through TransUnion CIBIL’s consumer dispute process and contact the relevant lender when the account information needs its attention. Clearly identify the entry you are challenging and provide supporting documents, such as statements or payment confirmations, where appropriate. Keep a copy of your communication and any reference number.
After submitting a dispute, follow the bureau’s and lender’s instructions and check the report again to see whether the information has been corrected. If the lender reported inaccurate information, the bureau may need the lender to verify or update it. Do not assume a dispute has been resolved until you have reviewed the updated report.
A simple routine to keep your credit profile on track
| Step | Action |
|---|---|
| 1 | Review your report for inaccurate or unfamiliar information. |
| 2 | Pay loan instalments and card bills by their due dates. |
| 3 | Keep card balances modest relative to available limits. |
| 4 | Avoid several credit applications in a short period. |
| 5 | Dispute report inaccuracies with the bureau and relevant lender. |
| 6 | Continue responsible credit use and allow time for updated information to appear. |
Consider checking your report periodically and whenever you are preparing for a major credit application. If you find a problem, address the specific issue rather than paying a third party for a guaranteed score improvement. No one can promise a particular score or approval outcome based on these steps.
How long does it take to see a change?
There is no fixed timeframe that applies to everyone. Improvement depends on your existing credit history, the behaviour recorded, whether there are errors to correct, and when lenders send updated information. A corrected entry or a new period of on-time payments may take time to appear in the report and affect the score. Be wary of claims that promise a guaranteed jump within a set number of days.
Conclusion
The most dependable way to work towards a healthier CIBIL Score is to manage the credit you already have: review your report, pay bills and instalments on time, keep card balances under control, and apply for new credit only when you need it. If you find incorrect information, raise a dispute and check that the report is updated. These actions can strengthen the accuracy and consistency of your credit history, but they cannot guarantee a specific score, timeframe, or lender decision. Keep the habits realistic and sustainable, and treat your score as one part of your wider financial profile.
Frequently asked questions
What is a good CIBIL Score in India?
CIBIL describes its score as generally ranging from 300 to 900. Lenders set their own eligibility criteria, so no particular score guarantees approval. Check the lender’s requirements for the product you are considering.
Can I improve my CIBIL Score quickly?
There is no guaranteed quick fix or fixed improvement timeline. Results depend on your credit history, lender reporting, and the information in your report. Consistent on-time payments and accurate reporting are practical steps to focus on.
Does checking my own CIBIL report lower my score?
Lender credit enquiries, commonly associated with applications, are a relevant factor. Use CIBIL’s official consumer service and check its current guidance for accessing your own report; distinguish a personal report review from a lender application.
What should I do if my CIBIL report has an error?
Raise a dispute through CIBIL’s consumer dispute process and contact the lender responsible for the account information. Share relevant supporting documents, keep a record of your complaint, and review the report again after the response.
Should I take a new loan to improve my credit mix?
Not just to change your score. Credit mix is one factor CIBIL identifies, but unnecessary debt adds costs and repayment obligations and does not guarantee an improvement. Borrow only when the credit serves a genuine need and fits your budget.
What is credit utilisation?
Credit utilisation is the proportion of available revolving credit, such as a credit-card limit, that you are using. Keeping balances modest relative to your limits is a practical habit, but no specific percentage guarantees a score increase.